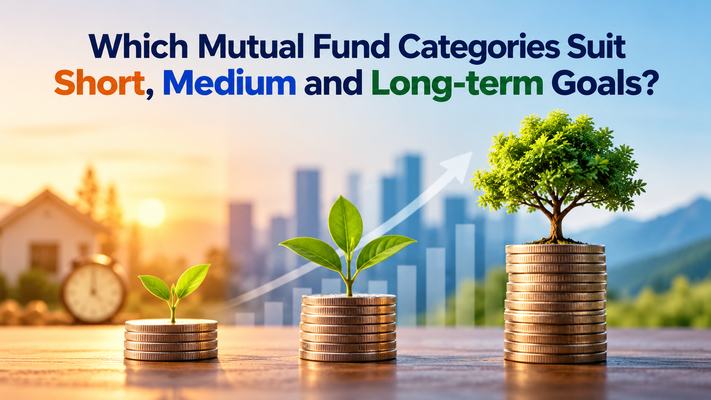
Which Mutual Fund Categories Suit Short, Medium and Long-term Goals?
Choosing an investment category becomes easier when you begin with the goal rather than recent performance. A holiday planned next year requires a different approach from funding a child’s education after ten years. The right mutual fund category should reflect when you need the money, how much fluctuation you can accept and whether the goal date is flexible.
Although historical mutual fund returns can support comparison, they cannot guarantee future performance. Investors should therefore consider the investment horizon, risk level, liquidity and exit load before selecting a scheme.
Let’s understand which categories may suit short, medium and long-term financial goals.
Why Does the Investment Period Matter?
Every investment category responds differently to market movements. Equity-oriented schemes may experience considerable short-term fluctuations but have more time to recover when held for several years. Debt-oriented schemes are generally less volatile than equity, although they still carry interest-rate and credit risks.
Your investment period determines how much time the portfolio has to manage temporary market declines. It also influences the balance required between capital stability, liquidity and potential growth. Matching the category with the goal can reduce the possibility of withdrawing during an unfavourable market period.
Which Mutual Fund Categories May Suit Short-term Goals?
Short-term goals are usually those expected within a few months to three years. Examples include creating an emergency reserve, paying annual insurance premiums, planning a holiday or arranging funds for a vehicle’s down payment.
For these goals, protecting the invested amount and maintaining easy access to money are usually more important than seeking high growth. A suitable mutual fund category may include:
- Overnight Funds: These invest in securities with a maturity of one day. They may suit money that needs to remain invested for a very brief period.
- Liquid Funds: These invest in debt and money-market instruments with maturities of up to 91 days. They may be considered for emergency reserves or near-term expenses.
- Ultra-short-duration Funds: These maintain a short portfolio duration and may suit goals that are several months away.
- Low-duration Funds: These can be considered when the investment horizon is slightly longer, although interest-rate and credit risks still apply.
Past mutual fund returns should not be the only selection criterion for short-term goals. Review portfolio quality, duration, expense ratio and exit load. Equity categories are generally unsuitable when the money is required soon because market declines may occur close to the withdrawal date.
Which Mutual Fund Categories May Suit Medium-term Goals?
Medium-term goals generally fall within a three-to-five-year period. They may include building funds for higher education, renovating a home, starting a small business or making a property down payment.
A medium-term portfolio may require a balance between relative stability and measured growth. Depending on risk tolerance, the following categories may be considered:
- Corporate Bond Funds: These primarily invest in highly rated corporate bonds. However, they are not free from credit or interest-rate risk.
- Banking and Public Sector Undertaking (PSU) Funds: These invest mainly in debt instruments issued by banks, public sector undertakings and specified financial institutions.
- Short-duration Funds: These maintain a portfolio duration of one to three years and can suit investors seeking debt exposure over a moderate period.
- Conservative Hybrid Funds: These invest predominantly in debt, with a smaller allocation to equity. The equity component introduces additional volatility but may support growth.
- Balanced Advantage or Dynamic Asset Allocation Funds: These adjust equity and debt exposure according to the scheme’s stated investment model.
The appropriate mutual fund choice depends on how fixed the goal date is. A non-negotiable expense may require greater debt allocation, while a flexible goal may allow limited equity exposure. When comparing mutual fund returns, assess performance across complete market cycles and against an appropriate benchmark instead of focusing on one strong year.
Which Mutual Fund Categories May Suit Long-term Goals?
Long-term goals are generally five or more years away. Retirement planning, a child’s future education and long-term wealth creation are common examples. A longer horizon gives investors more time to withstand market fluctuations, making equity-oriented categories more relevant for suitable risk profiles.
Possible categories include:
- Large-cap Funds: These invest predominantly in established, large companies and may suit investors seeking equity exposure with relatively lower volatility than smaller-company categories.
- Flexi-cap Funds: Fund managers can allocate across large-, mid- and small-cap companies based on the scheme’s strategy.
- Large and Mid-cap Funds: These combine exposure to established businesses and mid-sized companies with higher growth potential and risk.
- Mid-cap and Small-cap Funds: These can experience sharp price movements and may suit investors with a high risk tolerance and a sufficiently long horizon.
- Index Funds: These aim to track a selected market index and offer a passive investment approach.
- Equity-linked Savings Schemes: ELSS funds invest mainly in equities and provide tax benefits under the applicable provisions, with a statutory three-year lock-in.
A long horizon does not make every mutual fund suitable for every investor. Capacity to handle losses, income stability and the importance of the goal remain relevant. Moreover, strong historical mutual fund returns do not establish that a scheme will perform similarly in the future.
How Can You Match Mutual Fund Categories With Your Goals?
The following framework can help narrow the available choices:
| Goal period | Main priority | Categories to explore | Key risks to review |
| Up to 1 year | Liquidity and stability | Overnight or liquid funds | Credit risk, exit load and taxation |
| 1–3 years | Relative stability | Ultra-short or low-duration funds | Interest-rate and credit risk |
| 3–5 years | Stability with measured growth | Short-duration, corporate bond or conservative hybrid funds | Debt risk and equity volatility |
| More than 5 years | Long-term growth | Large-cap, flexi-cap, index or other equity categories | Market volatility and concentration |
| More than 7 years | Higher growth potential | Mid-cap or small-cap funds for suitable investors | Substantial fluctuations and prolonged declines |
Disclaimer: The categories and investment periods shown above are indicative and should not be treated as investment recommendations. The suitability of a scheme depends on an investor’s financial goals, risk tolerance and personal circumstances. Mutual fund investments are subject to market risks. Read all scheme-related documents carefully before investing.
Build Your Portfolio Around the Goal
Start by recording the goal amount, target date and acceptable level of risk. Then select a mutual fund category whose investment approach matches those requirements. Review progress periodically and consider gradually moving money towards lower-volatility options as the goal approaches.
Category selection is only one part of investment planning. Costs, taxation, investment strategy and portfolio quality also require attention. Online investment platforms such as JioBlackRock can help investors explore different scheme categories and invest based on their financial goals. However, consider consulting a SEBI-registered investment adviser if you need personalized guidance.